1. In the coming months and years the UK has decisions to make about how individuals with money purchase pension rights will be guided to their default retirement income products. It also needs to consider how we illustrate those future incomes to individuals during their savings phase. In this article I argue that we need to consider these questions together, as a system, and not separate matters. Government, regulators, and pension schemes need a vision about what that system looks like, in order that its components work towards a common objective. In particular, I argue that: an income in retirement that is expected to maintain its purchasing power over the lifetime of the retiree is a sensible starting point for guided retirement; that it is the best way of illustrating projected future income to current savers; that these two approaches will work well together; and that if we adopt them we will get better retirement outcomes for millions of ordinary savers.
2. Put that way it sounds uncontroversial. But, today, the most commonly purchased retirement products are not usually built around escalating incomes designed for inflation protection over the whole of a lifetime. And our statutory benefit illustrations project flat rate incomes in retirement whose purchasing power will fall with inflation. So I need to argue the case.
A falling income product
3. Imagine I was trying to sell a 65-year-old the following retirement product: a £10,000 guaranteed income in the first year, but reducing thereafter. Their first question would be: how does it reduce? By random amounts each year, that are hard to predict in advance and sensitive to market shocks and geopolitical events. So, based on past experience, what sort of income would they have at age 80? Well, about half the time it would have fallen to between £3,333 and £6,375, but it has been as high as £6,732 and as low as £1,949. And at age 95, usually between £1,134 and £3,436, but it has been as low as £968.
4. How does that sound? Is that a sustained income for the whole of retirement?
5. Well, it’s not that appealing to me, but apparently in the world of annuities the flat-rate is king. You may now have twigged that I have reduced the figures for the effect of inflation during the buyer’s retirement. I’ve described a flat-rate annuity in terms of prices at its commencement (the “past experience” used the Retail Price Index for 15- and 30-year periods since 1948).
A sustainable income
6. Was that income sustained? Only in a nominal sense – at £10,000 p.a. in our example – but not in any meaningful sense for our typical retiree, because their cost of living continues to rise. Deep into retirement, annual income could easily be under 10% of its initial value in real terms. Few of our spending needs are fixed in nominal terms over the long term. Most of our basic needs and expectations will increase — to some extent — with prices over time. I consider the contrary arguments below, and acknowledge that’s not exactly how spending changes – but it’s pretty close to it for most on the bit that matters most.
7. In my view, as a practical matter, an income in retirement is only sustained to the extent that it retains its value in real terms until death. That doesn’t mean it has to be fully maintained relative to some measure of inflation, but it does mean we can measure the extent to which it was sustained (or not) on that benchmark. An income that runs out before death clearly hasn’t been sustained throughout retirement, but an income that falls during retirement has only been partially sustained, at best.
8. In this article I argue that both guided retirement and benefit illustrations should be built around retirement incomes that will grow with inflation. I also consider the contrary arguments. A flat real-terms income does not exactly match spending patterns but is a close practical approximation and the easiest pattern to understand.
Guided retirement
9. In a few years’ time, most members of money purchase schemes will be steered towards “default pension benefit solutions” by their trustees or scheme providers. These must be “designed to provide a regular income for the eligible members concerned in their retirement (whether or not together with other benefits).” The Explanatory Notes to the Pension Schemes Act 2026 go further, in asserting (para 399) that they should provide a regular income for “the whole of” retirement. The Government’s July 2026 Guided Retirement guiding principles say it differently, but they are clear that “The government therefore considers protection against longevity risk to be a crucial element of default pensions, and so they must provide a retirement income that lasts throughout that retirement.” More broadly, “Guided Retirement … will ensure the vast majority of people are offered default pensions which are designed to provide a sustainable pension income.”
10. So, guided retirement seems, with reasonable exceptions, to be there to steer members towards a sustainable income throughout retirement. This means that the default should at least aim to maintain purchasing power over the whole of the member’s retirement. For most people, this could be plausibly past age 100, even if that isn’t the likely outcome.
11. I should emphasise here that I am making an argument about starting presumptions and official “steers”. Ultimately, it is for the trustees to determine default pension benefit solutions for their members, taking into account the needs and interests of the scheme’s membership, including their different circumstances.
Aiming at inflation protection
12. Does that mean inflation-linked annuities for all? No, but that’s one way of doing it, and it’s a good benchmark, because it’s the only widely available retirement product that will deliver a guaranteed income (with a high degree of confidence anyway, from a provider regulated by the Financial Conduct Authority – “FCA”) over the entirety of the member’s retirement.
13. However, I’m not arguing that’s the only way, or that we need to guarantee full inflation protection. There will be reasonable trade-offs that increase the expected income, albeit with additional risks.
14. One approach would be to target a certain level of increases, ideally with some mechanism that gives the product a fighting chance of responding to changes in inflation by increasing income (at least to some extent).
15. A collective pension bought at retirement (previously known as a “retirement collective defined contribution” or “R-CDC” pension) is one such way. By remaining significantly invested in growth assets and adjusting annual increases over time (as the sustainable rate of increase is reassessed), it can at least target at the outset increases to maintain purchasing power, and has a decent chance of being able to provide (at least some of) them. Clearly, those increases aren’t guaranteed, but retirement collective pensions would at least be “pointing in the right direction.”
16. Neither do increases need to be directly linked to an inflation index. A product guaranteeing or targeting 3.5% increases per year, for example, would also be “pointing in the right direction.” However, it’s even less certain to maintain purchasing power because it’s taking a very long-term view on inflation, and as my opening example showed, inflation is unpredictable over the long term and more so the further out we look. It might be suggested that my example figures are “distorted” by the inflation of the 1970s, and we don’t expect that again. Perhaps not, but I don’t think retirees of the 1950s and 1960s were expecting the inflation of the 1970s either. As recent years have shown, inflation can spike to unexpected levels, driven by real-world events rather than mathematical models.
17. What about “flex and fix” products? As with annuities and collective pensions, more flexible products could also target inflation increases in some way, with the degree of inflation protection varying by design. For example, flex-and-fix, designed to provide an income that increases with inflation before locking into an inflation-indexed annuity is likely to provide a sustainable income. A product that locks into a flat-rate annuity at age 80, for example, is not providing a fully sustainable income thereafter.
18. Similarly, an individual drawdown product could be designed to provide an inflation-adjusted income over the long term; however, without pooling the member’s mortality risk, it would have to assume the member lived to a reasonably foreseeable maximum age, or else fall short on the “throughout retirement” requirement.
Do members need all that inflation protection?
19. Don’t people actually need higher incomes earlier in retirement? Don’t spending needs decline during retirement? Isn’t retirement typically “go-go” then “go-slow” followed by “no-go”? Is retirement spending a smile or a smirk? It’s hard to disentangle the spending required to maintain a standard of living from pensioners’ actual spending. Some spend more or less at particular points because of what they have available to spend, rather than by choice. On one hand, I think of pensioners with pre-1997 accrual receiving no increases on their workplace pensions, and the decline in their living standards over their retirement. On the other I think of the rise in recent years of the state pension relative to prices. Generational effects also need to be allowed for: the 60- and 80-somethings of today will experience different standards of living throughout their retirement reflecting, for instance, changes in the state pension, the decline of DB, and the rise of auto-enrolment .
20. The Institute for Fiscal Studies (IFS)’s relatively recent report, based on UK data, How does spending change through retirement? suggests a complex picture, with spending at different ages heavily influenced by different generations’ incomes. Considering spending for each generation as they age, (section 3.1), key finding 1 (page 3) was as follows: “On average, retirees’ total household spending per person remains relatively constant in real terms through retirement, increasing slightly at ages up to around age 80 and remaining flat or falling thereafter.” Its accompanying presentation’s summary and conclusions included the following:
- Flat profile in real (Consumer Prices Index adjusted) terms — no evidence for average spending falling after a certain age.
- Flat income profile can be achieved with Pension Freedoms but no strong evidence [of] people wanting to front-load spending.
- Average age-profile of spending within generations is relatively flat.
- Based on these results, people should plan their drawdowns and saving in anticipation of constant real-terms spending in retirement.
21. Although spending on holidays, leisure and motoring falls at older ages, it’s notable that other basic household bills do not.
22. Other longitudinal studies highlight the different spending patterns of different groups, most notably homeowners and renters. Spending for essentials, luxuries and housing appeared fairly flat for social tenants as they aged. However, for homeowners (generally more affluent and with lower housing costs) spending on luxuries was markedly higher in earlier years. This suggests to me that the more affluent are able to and wish to spend more in the early years of their retirement, however, this spending spree in the earlier years of retirement could often be met from their tax-free lump sum (typically a quarter of the value of their pension) or other savings. Much of this additional spending will be linked to non-daily activities, such as holidays, home improvements, wedding gifts etc. Accelerated spending in early retirement by those who can afford it does not imply that they wish the purchasing power of their regular income to decline during their retirement.
23. The relatively affluent may reasonably be able to front-load their spending, or hold pension pots back for rainy days and bequests. Some have substantial defined benefit (DB) pensions. However, they will also need to cover their “core costs” as those rise with inflation over their retirement — they will likely have a higher standard of living than the lower-income groups, but it’s still a poor outcome for them if that standard of living becomes increasingly unaffordable in later life because they have (effectively) over-spent in earlier retirement. For people of more modest means, including most of those relying on their money purchase pots, constant real-terms spending appears to be a sensible starting point. Not because it’s perfect but because it’s understandable and a helpful place to start. As the Pensions Commission noted in its interim report (s5.49 citing DWP analysis), “Since the number of renters in retirement is expected to grow over time and given fixed costs such as housing or bills form a larger proportion of renters’ income, expenditure seems unlikely to reduce significantly over time for all pensioners.”
24. There is also a practical point here. The shape of spending needs is clearly influenced by the degree of affluence of the pensioners, and changing historical circumstances. The variation in spending patterns identified (whether a ‘u-curve’, ‘smile’ or a ‘smirk’ etc. for some people) does not mean there is a “better shape” we could reliably plan for across the broad membership of our schemes. In other words, the same longitudinal research that highlights real-terms spending is not quite flat for everyone also supports flat real-terms spending as a good approximation. For example, 2014 research in the US (a very different context to the UK’s) suggested a 1% per annum reduction in real spending. However, it is not easy to plan for and communicate a 1% p.a. decline relative to inflation, especially since the inflation levels over the future decades of an individual’s retirement are essentially unknowable in advance. A 1% p.a. real-terms reduction, even if perfectly correct for everyone, could be well approximated by an inflation-targeting income, especially in conjunction with 25% of the retirement pot withdrawn as a tax-free lump sum (and then a significant portion held in savings).
25. I hear the counter-argument that “state pension inflation protection is enough,” but that’s equivalent to saying “it doesn’t matter if your private pensions savings run out,” because it implies there’s no lower limit to how far the income could fall. I am wary of arguments suggesting that lower-income retirees need less inflation protection than others, when they are least able to absorb a fall in living standards. I don’t think guided retirement accepts that premise either, and research confirms most people would be worried about having to live off the state pension alone.
26. The Guided Retirement guiding principles state that the Government’s policy is aimed at:
- overcoming complexity
- reducing the risks borne by individuals
- improving the sustainability of retirement incomes
27. Most people’s expected basic spending needs will be above the level of their state pension. Those spending needs are expected to increase broadly in line with inflation over their retirement. Therefore, if those expectations are to be met throughout retirement their workplace and private pensions will need to bridge the gap. It would be a poor outcome if their private pension diminished in value over their retirement so that their living standards became increasingly unaffordable in their final years. Worse, a flat rate private pension income would start with a (higher) income level that could not be sustained, guaranteeing that its purchasing power would significantly decline during retirement.
28. Another argument says lower income groups have lower life expectancies and therefore it is rational to plan for higher incomes for them earlier in retirement and not be concerned about income needs in the years beyond when most are expected to be alive. However, this misrepresents the risks to the individual members. Life expectancy is a distribution not a destination: whatever a person’s circumstances and however “accurate” their life expectancy estimate, there is a substantial chance they will live many years beyond that expectancy just through luck. The individuals living to those higher ages still have income needs even though – back when they retired – they might not have expected to be alive at those ages. (The IFoA discussed how “life expectancy” is widely misunderstood in its evidence to the Third State Pension Review).
But do members want a real-terms sustained income?
29. The “annuity puzzle” refers to the well-known contrast between consumers’ ostensible desire for secure lifelong incomes and their failure to purchase them when given alternative options. This concept can be extended to contrast individuals’ apparent desire not to risk falling living standards with the fact that most annuities actually purchased are flat rate. FCA data shows that most annuities purchased are not escalating. However, research into mid-retirees also shows an overwhelming majority thought the security of an income for life was important and was becoming more important to them as they got older. Only 2% said they were very comfortable with a “fluctuating” income.
30. This doesn’t suggest to me that – contrary to what they might say to researchers – most people secretly want their retirement purchasing power front-loaded and to reduce by random amounts every year they get older. Instead, it suggests a problem with the choice architecture, leading people to take actions for short-term reasons to their long-term detriment. A report “Defined contribution guided retirement: A behavioural perspective” sponsored by the Institute and Faculty of Actuaries (IFoA), from the Behavioural Insights Team (BIT), “Defined contribution guided retirement: a behavioural perspective”, highlights how present bias can cause an immediate and certain benefit to outweigh a larger but more distant cost. In this context, the visibly higher starting income from a level annuity may be felt more strongly and immediately than the more distant and uncertain loss of purchasing power many years later.
Talking in today’s money
31. In The Life and Opinions of Tristram Shandy, Gentleman, Uncle Toby has inherited “a small estate of about one hundred pounds a-year.” Is that a lot or a little? My first house had a 70p a-year ground rent that the freeholder didn’t bother to collect, but had within the living memory of older neighbours. But what was it worth before Victoria came to the throne?
32. No idea. But the answers will depend on when we’re talking about and how prices have changed in between.
33. I suggest few readers will have any real idea of the answers and little interest in these questions. Similarly, I think few of us (even actuaries!) are able to think clearly about how much £10,000 would be worth, in today’s money, ten, twenty, thirty, or forty years ahead. We can only “really” (a conveniently double-meaning word) understand what a future amount of money is worth if we can “currency convert” it to today’s prices.
Behaviours and biases
34. The BIT report describes “inflation blindness”. It notes evidence that, among people holding at least £10,000 in cash without financial advice, a third did not know that cash savings tend to lose value over time because inflation normally outpaces interest rates. The report concludes: “There is a significant risk that the public does not sufficiently understand longevity risk, does not sufficiently understand inflation risk, and does not sufficiently understand that inflation risk is also a longevity risk.”
35. That links back to the solution design already discussed under “Aiming at inflation protection”: that a retirement product expected to result in these kinds of unpredictable but declining purchasing power is hardly ideal for good retirement-decision making.
36. It should also drive our approach to benefit illustrations. BIT draws an important distinction between financial literacy and financial “legibility”: whether people can readily understand their options, compare them and tell good from bad. That distinction matters here. We should not expect members to reconstruct the real value of a nominal income by applying uncertain future inflation over several decades. An illustration that expresses future income in today’s money makes the choice more legible at the point when it is made.
37. This brings us to the challenge of how to illustrate incomes to money purchase savers in advance of their retirement. An income maintained in real terms is simple to understand: if it starts at £10,000 a year and increases with inflation, it should retain roughly the same purchasing power throughout retirement.
38. On the other hand, telling people what their (in today’s money) income at retirement is but building in some unknown but definite reduction over the course of their retirement is, at best, not helpful, and at worst, dangerously misleading. I don’t think it would pass a Makerfield Test.
39. BIT proposes a sharper standard for the sector: not merely “did we inform the member?”, but “did we make it easy for the member to tell the difference between good and bad?” An illustration that gives prominence to the starting nominal income while leaving its long-term erosion for the member to infer would struggle to meet that standard.
Statutory illustrations
40. Before 2014, the statutory money purchase illustration standard (“SMPIs” under “TM1”) required that members’ projected benefit illustrations assume their pots would be used to buy index-linked annuities. From then until 2023 there was a choice of illustrating with either an index-linked annuity or a flat-rate annuity. However, in 2022, the Financial Reporting Council (FRC), prompted by the approach of pensions dashboards, consulted on a single approach to annuitisation. It decided to “prescribe the form of annuitisation to be a level annuity without attaching spouse or partner benefits so [as] to align with current market practice.” It noted that the “vast majority of annuities actually purchased are level in monetary amounts (i.e., not including any increases in payment) and do not include attaching spouse or partner benefits.” Simultaneously schemes were stopped from assuming that the member would take a tax-free lump sum from their savings at retirement.
41. Moving from joint-life, index-linked pensions to single-life pensions typically led to an increase of about 80% in the annuity shown, but it didn’t make the members (or their partners) any better off. Instead, our member, who had previously been shown a £10,000 p.a. income with inflation increases was shown an £18,000 income, that would likely be worth around half of that a couple of decades into retirement, and even less at older ages (and nothing for a surviving spouse). Worse, it makes the member contemplating a £10,000 p.a. index-linked annuity think that it would make them worse off than they’ve been led to expect.
42. I disagreed with the FRC decision, but I understood their reasoning in a world where members were mostly responsible for how they used their money.
43. However, the world is now moving on, and trustees and providers will likely have a big impact on retirement choices. With the Government’s heavy steer towards a sustainable income throughout retirement one must assume that some level of expected inflation protection — however approximate and unguaranteed — ought to become much more common. The logic of 2022 now leads in a different direction.
44. Nor should observed purchasing behaviour necessarily determine the illustration standard. The BIT report argues that pension freedoms have operated as a large natural experiment in individual decision-making, but that the difficulty has not primarily been a lack of information. The system has not made the choices sufficiently legible. If purchasing decisions are shaped by present bias, loss aversion and inflation blindness, reproducing the most common purchase in statutory illustrations risks embedding the behavioural problem rather than correcting it.
45. It’s pleasing to see the FRC is now getting a mention in the updated workplace pensions roadmap, connecting FRC to the guided retirement agenda. Publication of FRC’s standards for illustrations for common forms of decumulation options (including R-CDC) plus illustrations during the decumulation phase is currently expected between July 2028 and September 2028.
46. Does my argument mean that trustees should be expected to steer members towards index-linked annuities? No, but the old TM1 approach of an index-linked annuity — with a light dusting down — would provide an illustration of what a guaranteed income for life with inflationary increases would look like. I don’t mean that every member will buy this (I’d be very surprised if they did). But it’s a fair standard, that most members could understand. “The insurer will pay you this income, every month for life, and they will increase it to the extent general prices go up.” Members might take their income in a different way, e.g. flat-rate annuities, retirement collective pensions, flex-and-fix, individual drawdown etc.: those alternatives will usually involve a higher initial income that could be obtained with the same pot from an index-linked annuity, but not without additional risks (inflation, investment, mortality etc.). Those explanations should be tested with members, not assumed to work for them. BIT’s proposed standard is whether members can understand what the default does and distinguish a good outcome from a bad one. Its review also cautions that adding more information can reduce engagement: the answer is not necessarily a longer warning, but a more salient and intelligible presentation of the trade-off.
Matching illustrations to guided retirement defaults
47. This leads to the challenge of how to square the index-linked annuity illustrations against likely guided retirement defaults and what people will actually do with their retirement savings. I think you can distinguish between illustrations provided many years before retirement and those provided as members approach retirement. For the former, it’s too far away to really know what the default will be for the member when they get there, and a consistent benchmark is helpful. For members approaching retirement, the emphasis could switch to the default: there’s already a longstanding statutory exemption under the disclosure requirements for certain members who are within two years of their retirement date, which seems a reasonable switch point. Assuming the guided retirement default involves more risk to the member than an index-linked annuity we’d expect illustrated incomes to increase — not ideal, but better than the other way around. And if that default is required to target inflation increases then the step-up should be much less than the 80% jump we saw in 2023/4. (I would also argue that illustrations of the guided retirement default should show members their maximum lump sum option and default them to providing a survivor’s income for their dependant if they have one).
48. Many products won’t be expected to provide increases that exactly match inflation (some will provide no increases at all). Ideally, we’d help members understand the effect of inflation in eroding those incomes; however, I accept it would be baffling to the average member to project incomes forward and then re-express them for each year in today’s prices. Instead, illustrating those defaults would require a written description of the way the income would increase (or not) and a warning about the way inflation would or might erode the purchasing power of the income.
Pension Dashboards
49. Pension Dashboards will show Estimated Retirement Incomes (ERIs) for members’ future benefits, and for money purchase benefits that illustration will be based on the SMPI.
50. The FRC said that “As such it is important that illustrations presented on the pension dashboard are shown on a common basis to facilitate this comparison being made fairly in a way that does not mislead the individual.” I agree, but that won’t work when money purchase benefits sit next to DB benefits, since most of these will increase in payment — typically, full indexation in the public sector, and indexation up to an annual cap for post-1997 accrual in the private sector. Illustrating the money purchase benefits assuming inflation increases would therefore make them more comparable against the DB. It isn’t critical if the DB isn’t fully inflation-protected or uses a different inflation index: the comparison doesn’t have to be perfect to be better.
Conclusion
51. I’ve argued here that we need guided retirement and benefit illustrations to work together as a system:
i. Constant real-terms spending in retirement should be the starting assumption for retirement income needs. Not because that’s a perfect assumption but because we don’t have a better practical one.
ii. Inflation protection is part of longevity protection.
iii. Retirement incomes are sustained to the extent that they maintain their purchasing power throughout retirement.
iv. Guided retirement default products should therefore usually aim to provide a broadly inflation-maintained income throughout the whole of retirement.
v. Benefit illustrations for money purchase members should express incomes throughout retirement in today’s money.
vi. Illustrations and guided-retirement communications should be judged by their legibility: whether members can compare the options and recognise the consequences of inflation, rather than merely by whether the prescribed information has been supplied.
vii. Returning to an index-linked annuity illustration, as was previously the TM1 standard, is generally appropriate, not because it’s what every member will or should purchase, but because it is a good benchmark for what real income a pot could be expected to provide throughout retirement with a high degree of confidence.
viii. However, closer to retirement it is more appropriate to illustrate benefits using the default for the member. Lump sum options should be shown if they are part of the default strategy. Defaults should nudge people to provide for their dependants.
ix. Pensions dashboards should show money purchase illustrated incomes on the same basis, improving comparability when shown alongside DB incomes that increase in payment.
52. This isn’t to argue it is the best outcome for everyone, nor that trustees should not carefully consider the right default solutions for their membership (it will be their statutory duty to). But it’s an argument about the framework in which those guided retirement decisions will be made. I’m also mindful that not everyone needs constant real-terms spending in retirement, particularly the more affluent. However, consider a Makerfield Test (or more philosophically, drawing on the ideas of John Rawls): what policies and rules are going to help make a positive difference to the lives of ordinary people, particularly those least well-off? If we have to choose between something that works better for those on modest means and something that works better for the more affluent, then we should choose the former. That focus is also consistent with BIT’s warning that the people with the least time, money and cognitive bandwidth have the least capacity to navigate complex retirement choices, despite having the smallest margin for error. Defaults and illustrations should therefore be stress-tested against members for whom the pension is not discretionary wealth but their principal retirement strategy. Overall, I suggest the solution would look something like the above.
This article sets out my personal viewpoint. It does not necessarily represent the views of either my employer or my professional body.
A condensed version of this article will be presented in the IFoA’s ‘Think’ series.


 I am disturbed but not surprised to read concern from S&P at the increased dependency on private credit to back promises to pay our pensioners.


 Louse Haigh , the most prominent member of his current advisory team has been loquacious on an economic reset since leaving parliament in November 2024. Speaking at the 2025 Compass Conference in London, before writing an essay for the New Statesman in September 2025 on the ‘fiscal straitjacket’ facing the Labour Government and the need to reform the Office for Budget Responsibility and its role in economic policymaking. She followed it up with a second essay in February 2026 in which she accused the OBR of “throttling” the UK economy by not considering the long term impact of public investment in its economic forecasts.
 In 2007, he was named Consumer Champion of the Year by


 91% of respondents said they are likely to consider CDC or similar schemes for their business, up from 81% in 2024.


 I have been lying awake worrying about several pensions I know that are in an “end-game” that will lead them to firstly buy-in of annuities and then “buy-out” of the scheme by an insurance company with a “buy-out”. Such is the weight of opinion that ridding employers of their pension liabilities that there is little opposition from those whose pensions are to be swapped for promises from an insurance company.


 Sarah Smart is a pretty special person, chair of our Pensions Regulator she gave the VFM podcast 90 minutes of high power insights into herself and her role at the Pensions Regulator.






 Hours before TPR’s announcement ,




 A 55 year old today with a retirement pot of £30,000 has 12 years to wait for their state pension but could reasonably expect to pay themselves £250 per month from their retirement account without too much fear that the account would run dry at 67. I mention these figures as they approximate what’s in the pot for the average person by the time they get to 55. But of course the number is wrong for the poorest in society because so much employment has not been pensionable – especially if someone has been out of work, in self-employment or in work before auto-enrolment staged. The situation is particularly grim for women.


 Yesterday was the first of the TUC’s pension conference and in a single session, the conference debated “investing in a just transition to a low carbon economy”. Guy Opperman spoke and was well received by Chair Paul Novak and by the 150 odd delegates who were noticeably easier about his agenda in the chat rooms than they had been openly on his previous visits to Congress House.

 Aviva supported a UK renewable energy project with a £131m loan to finance offshore transmission assets for a wind farm off the Suffolk coast. Each year, the Galloper Offshore Wind Farm’s 56 turbines generate enough green electricity to power the equivalent of more than 380,000 British homes.






 The asset valuation above occurred close to the bottom of the pandemic panic. Asset prices have since then recovered. There have been recent comments that the asset portfolio recently had a value of £74 billion – in which case the required rate of return would now be 2.68%



 Almost as important as its findings, the constitution and delivery of the small schemes working group is an exciting foretaste of a new way of working for the DWP and its pension policy unit.


 On Wednesday (October 8th), CDC will be debated in the house of commons and with a fair wind, legislation enabling employers and multi-employer master trusts to provide DB like benefits for defined contributions will be enacted by the end of the year.


 It seems that we are in for another round of will he won’t he over wealth taxes. He being Rishi Sunak and the taxes in question surrounding business profits, wealth in excess property and the distribution of pension tax relief.




 Consumers will find that they can view and manage their investments with the automation they expect for their home.


 There is a long history of successful projects where state and private sectors have worked together to deliver good. That history continues to this day as is evidenced by the banking activities of McQuairie and the Insurance activities of Legal & General.






 As AgeWage prepares for its journey into the FCA Sandbox, we are becoming more aware of the vulnerability of ordinary people to pension scams. We are really worried about the impact of unemployment, especially on those who are over 55 and within reach of their pension freedoms.


 NB: Figures for Scotland use a different definition of weeks, running from Monday to Sunday rather than Saturday to Friday. The chart above is based on using the week ending on the Sunday immediately after the date shown on the horizontal axis.
 Given the ongoing concerns around availability of PPE in care homes, alongside the challenges care homes can face in isolating those symptomatic of COVID-19, it seems likely that we will continue to hear sad news of tragedy emerging in UK care homes.






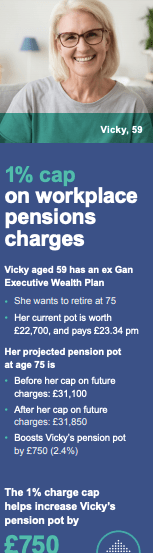
 Take as an example David. David is 61 and wants to retire at 75.




 Bespoke or off the peg?








 Of course it shouldn’t have to be like this








 …the mass of data stored by pension providers is often fragmented and split across multiple formats. However, developing tech can help scheme managers to bring different data sources together, analyse data and predict future trends, ultimately helping them to run schemes more efficiently. Legal & General, for example, has moved 2.4 billion rows of data since starting its own project to create a cloud-based digital platform for pensions – and this only covers a third of our book of business.
 “Schemes can’t just wait for legislation, they need to improve their data quality now so that it is ready. [The] dashboard will help savers, therefore it’s in everyone’s interest that pension schemes are getting accurate, up-to-date information in place to help ensure the new services work well.”










 Barclays has kindly agreed to host us at Plexal, the innovation centre in the Olympic Park. Pension Bee has invited a broad representation from the pensions industry to judge our efforts, including Michelle Cracknell CBE, Margaret Snowdon OBE (President of the Pensions Administration Standards Association), Dominic Lindley (Member of the Financial Services Consumer Panel and Member of the Pensions Dashboard Industry Delivery Group) and Stephanie Baxter (Deputy Personal Finance Editor at The Telegraph), each of whom brings a unique perspective to the challenge at hand.


 I’m keen to point out that the reason I’m in the BBC’s Salford studios is because I want to be live in Manchester discussing the good that pensions can do. I will be talking with a female presenter , Winifred Robinson (pictured) and the research has been through another young female – Beatrice Pickup.






















 ) , and went to an IFA and was armored, protected empowered and that so , I’m eternally at your debt for . Kind regards….
 happy retirement Kevin
 Yesterday was a good news day for people concerned about retirement income. The FCA made two meaningful statements on what it intends to do to help ordinary people trying to manage their in retirement finances. The first was the


 Higher earners can get their higher rate tax-relief paid to them up-front through salary sacrifice, while lower earners get their incentive through relief at source. There are complex triggers in place at payroll to make sure that those on low earnings don’t lose out from salary sacrifice (or that Tesco doesn’t accidentally pay them a nominal salary below the minimum wage.


 People on drawdown are less happy


 Commenting on the launch of the scheme, Hymans Robertson head of collective defined contribution (CDC) Lauren Branney said it is “encouraging” to see the government recognise the opportunity CDC pensions can offer for both workers and employers in the adult social care industry.


 In case anyone thought that the freeholders would let our Government do what is fair, this leasehold bill is sadly a watered down version of “good”; it’s given in to those who make money out of leaseholders, ratchet up rents and drives flat resale value down.


It is very simple really!
Standard life is pinching the assets of its pension scheme through the profits on the buy-in policy without having to pay tax on surplus distributions. It is also not having to share those profits with the scheme members.
A warning message for any other trustee boards thinking of purchasing bulk annuities – what is the profit margin you are losing to the Scheme!
The purchase of annuities brings with it FSCS protection. 100% of the pension is covered with no upper limit. I have seen a legal opinion that confirms this even in the case of the annuity being provided by a connected company as in this case. Previously the covenant was with the employer and could perhaps have been described as very strong. Now it’s even stronger!
I am very surprised by your legal opinion on the availability of FSCS coverage for buy-in policies.
The FCA Handbook states:
COMP 4.2 Who is eligible to benefit from the protection provided by the FSCS?
COMP 4.2.117/03/2026R
An eligible claimant is any person who at any material time:
1. (1) did not come within COMP 4.2.2 R; or
2. (2) did come within COMP 4.2.2 R, but satisfied the relevant exception in COMP 4.3.
3. [Note: See COMP 4A.2.2G about special cases in COMP 12A.1 (Trustees and pension schemes) and COMP 12A.3 (Collective investment schemes).]
Persons not eligible to claim unless COMP 4.3 applies (see COMP 4.2.1R)
COMP 4.2.2 17/03/2026 R
This table belongs to COMP 4.2.1R
…
(4) Pension and retirement funds, and anyone who is a trustee of such a fund
…
(9) Bodies corporate in the same group as the relevant person in default or, in respect of a claim against a successor in default, bodies corporate in the same group as a successor or the relevant person, as applicable
…
(13) Large companies, large partnerships and large mutual associations
Trustees of pension schemes
COMP 4.3.1017/03/2026R
1. A person is eligible to claim compensation for claims where they are a trustee of:
1. (1) a personal pension scheme;
2. (2) a stakeholder pension scheme (which is not an occupational pension scheme);
3. (3) an occupational pension scheme insofar as members’ benefits are money-purchase benefits; or
4. (4) an occupational pension scheme insofar as members’ benefits are not money-purchase benefits; and the employer is not a large company, large partnership or large mutual association.
“… securing the benefits of around 2,750 members…”
Did the Trustees not feel that the benefits were secure with Standard Life…?
More Trustees are considering that, although the legal aspiration of 100% FSCS cover for a buy-in is clearly set out, whether the practical capacity is finite and untested at the scale now involved, and so Pensions remain safer under the pension regime?
FSCS protection for a bulk annuity buy-in is often presented as 100% with no upper limit. That is generally (noted exceptions) true under the rules for qualifying long-term insurance. But the practical reality is very different from the funded safety-net members enjoy while benefits remain inside a DB scheme under the Pensions Regulator and the PPF.
The current annual levy limit for the Life & Pensions Provision class is only £690 million, which is orders of magnitude smaller than the potential shortfall if a major BPA writer (or several) failed and residual assets after insolvency, reinsurance and recoveries proved insufficient. A single large BPA portfolio can easily run to tens of billions of liabilities. The net cost to FSCS would be the gap after recoveries — not the gross figure — yet a multi-billion or tens-of-billions shortfall would still overwhelm ordinary annual levy capacity many times over.
In such (black swan?) cases the system would have to rely on multi-year levies, any available retail-pool/cross-class contributions, borrowing facilities, recoveries over time, and ultimately the willingness of government and the Insurance industry (including the non-uk participants) to keep payments flowing. Although there is no automatic legal mechanism that scales compensation back pro-rata if funds run short so a notional 100% entitlement remains, the FSCS funding model is pay-as-you-go and is simply not pre-funded to the scale of the risks now concentrated in the BPA market (cumulative liabilities already around £270–300bn).
This is why commentators are increasingly questioning whether FSCS could cope with a major bulk-annuity default without broader systemic support. By contrast, benefits still inside an occupational DB scheme sit under the Pensions Regulator’s covenant and funding regime, with the surplus funded PPF as a properly capitalised, pre-funded lifeboat that currently holds a multi-billion-pound surplus buffer and has clear statutory levy powers across £1.2trn of other pension schemes.
I’m sure Chris Martin, the ReAssure Staff Pension Scheme chair of trustees, is a super fellow.
His firm’s website states that Chris also leads IGG’s trustee appointments on several “high-profile” cases including Co-op Group, Coats plc, Legal & General plc, Atos SE, Northern Foods Limited and Bayer plc.
His style is described by colleagues and peers alike as “inclusive and collaborative”.
By conventional understanding, a collaborator is one who assists an enemy, helping groups to which he does not belong threaten groups to which he does belong.
But I hope I’m completely wrong about this.
As for the “high-profile” cases, a very cursory glance (for which I can only apologise as I wait to watch the delayed and much curtailed final stage of Tour de France 2026) revealed the following:
Co-op: buy-in with Rothesay in 2023.
Coats: buy-out with PIC in 2024, after an earlier buy-in with Aviva
L&G: DB closed, current employees in DC only. I can’t find any mention of legacy staff DB scheme(s) in the 2025 group financial statements, so presumably the amounts (and the accounting policy) are simply not material within the scale of L&G. DC staff pension costs in 2025 were a mere £77m, down from £105m the year before.
Atos – closed DB with deficit recovery payments scheduled to 2032. Market value of assets (which includes some Continental European schemes) declined during 2022 from £3.616bn to £2.440bn, largely because of the allocation to bonds and interest rate swaps, a form of LDI.
Northern Foods – closed DB schemes with deficit recovery payments scheduled to 2034. Market value of assets declined from £1.328bn to £631m over 2022-2024, largely because of the geared allocation to bonds, another form of LDI.
Bayer – closed DB scheme, now in surplus. Total market value of assets has fallen over the years to £1.114bn in 2025, after a partial buy-in with Canada Life in 2023. The scheme is supported by a number of employers, but for example the share of scheme assets reported by Bayer PLC declined from £1.002bn to £649m in 2022, largely because of the allocation to debt instruments.
“Persons attempting to find a motive in this narrative will be prosecuted; persons attempting to find a moral in it will be banished; persons attempting to find a plot in it will be shot.” Mark Twain